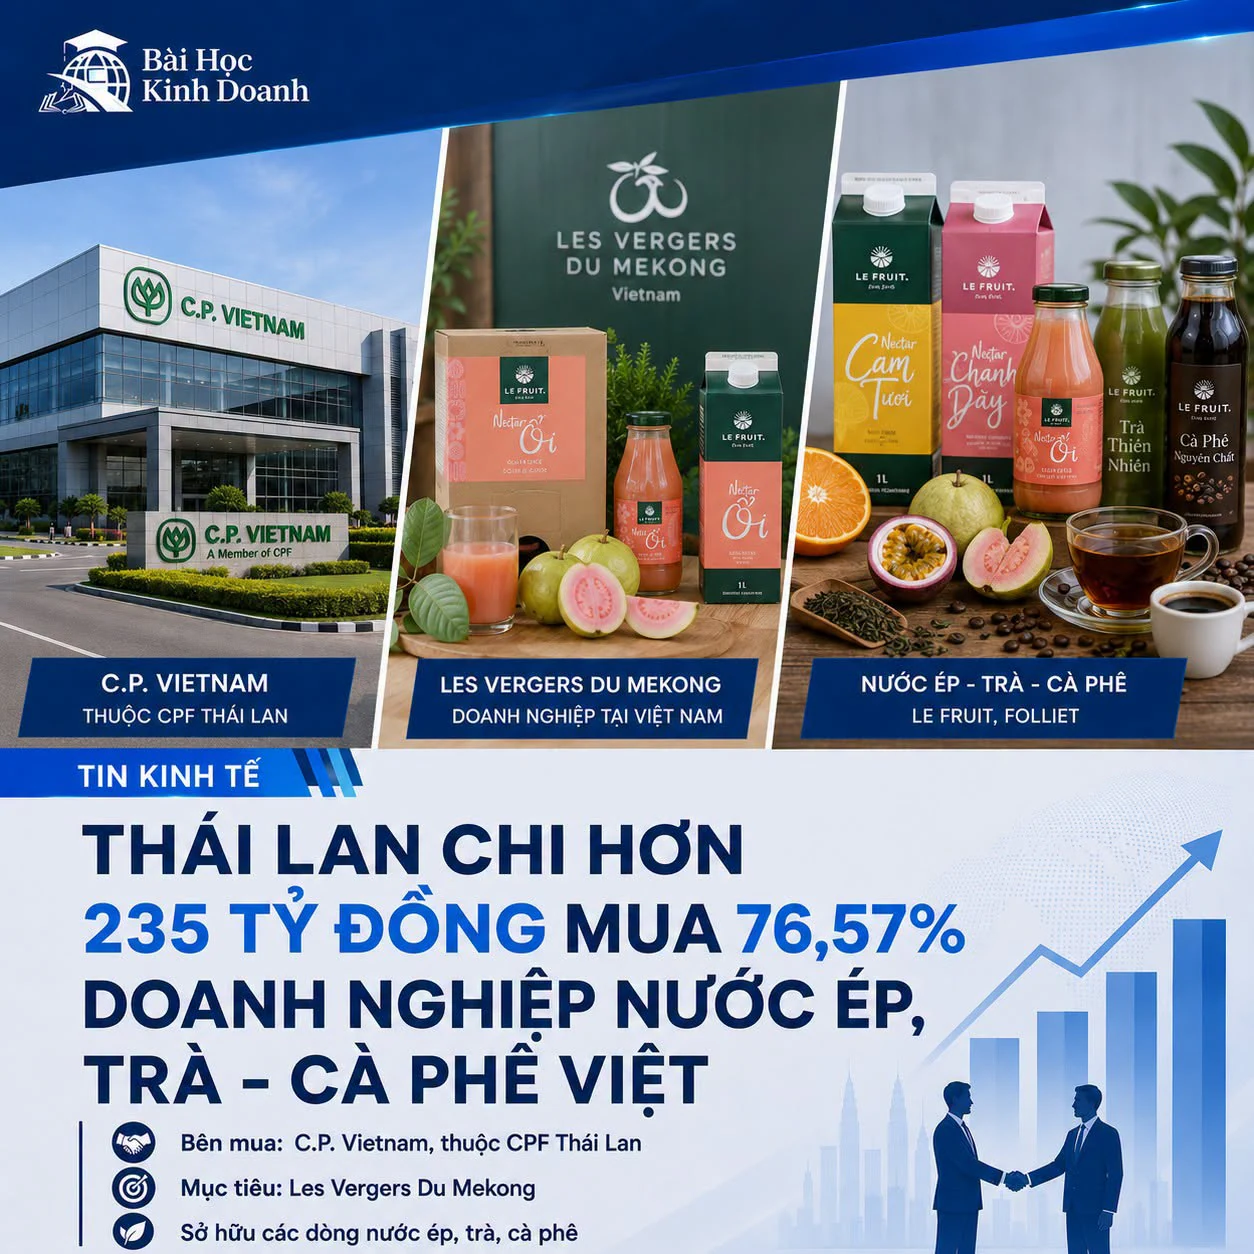
On August 12, 2026, C.P. Vietnam Corporation, an indirect wholly owned subsidiary of Charoen Pokphand Foods, signed an agreement to acquire 76.57% of Les Vergers Du Mekong for VND 235.058 billion, approximately 336 million baht. If conditions are met as expected by mid-October 2026, LVDM will become a subsidiary within CPF’s ecosystem. The deal shows how a domestic business with brands, a factory, a product portfolio and an established customer network can offer a regional group faster market entry.
Over VND 235 billion for control
According to the disclosures, C.P. Vietnam will acquire 768,793 LVDM shares from Folliet Group and Voisin Group. They represent 76.57% of capital, for VND 235.058 billion, approximately 336 million baht.
The purchased stake implies total LVDM equity value of approximately VND 307 billion. This is only a reference calculation from the share transaction price, not enterprise value after cash, debt and other terms.
The transaction was signed August 12, 2026 and is expected to close in mid-October after relevant conditions are met. LVDM would then become a C.P. Vietnam subsidiary within CPF’s ecosystem.
Who is behind Le Fruit and Folliet?
Les Vergers Du Mekong was established in 2000 and develops juices, purées, jams, tea and coffee. Le Fruit and Folliet are two notable names in its portfolio.
The company has a production facility in Cần Thơ, access to Mekong-region raw materials and distribution through hotels, restaurants, food service, retail and some export markets.
LVDM’s appeal is not confined to one brand. It combines product development, a factory, raw-material supply chains, HORECA customer relationships and operating experience in Vietnam.
What does pre-transaction growth indicate?
LVDM revenue rose from approximately VND 127 billion in 2023 to VND 154.5 billion in 2024 and VND 199.3 billion in 2025. Two consecutive years of revenue growth indicate market expansion before the new investor.
Net profit rose from approximately VND 11.3 billion in 2023 to VND 15.2 billion in 2024 and VND 20.4 billion in 2025. Profit thus nearly doubled over two years, and the 2025 net margin was approximately 10%.
Dividing implied equity value of approximately VND 307 billion by 2025 profit gives a reference multiple of about 15 times. This helps illustrate the transaction’s scale, but is not a complete valuation without debt, cash and post-transaction terms.
Why did CPF choose acquisition over building from scratch?
CPF says the investment deepens its presence in beverages and opens export opportunities. C.P. Vietnam already has a substantial agriculture and food base; LVDM adds beverages and experience serving HORECA customers.
Developing a new brand requires time to test products, meet standards, build a factory, find distributors and establish customer trust. M&A provides simultaneous access to these capabilities, while still requiring integration and preservation of brand identity after the deal.
For the seller, valuation reflects not only tangible assets but also customers, recipes, market data, the team and the ability to move products from growing regions to points of sale.
Lessons for Vietnamese businesses: build assets that can be valued
Revenue matters, but strategic buyers often examine revenue quality, growth potential, margins, founder dependency and distribution-system durability more deeply.
An attractive business must demonstrate clear brand ownership, reliable financial data, verifiable production processes, sustainable customer relationships and a team able to continue after shareholder changes.
The long-term challenge is therefore more than how much you sell. It is building a business clear enough for the market to understand, efficient enough for investors to see cash flow and systematic enough that value does not disappear when the founder leaves the meeting room.
- C.P. Vietnam signed to acquire 768,793 shares, equivalent to 76.57% of LVDM, for VND 235.058 billion
- Founded in 2000, LVDM owns a factory in Cần Thơ and the Le Fruit and Folliet brands
- LVDM revenue grew from approximately VND 127 billion in 2023 to VND 199.3 billion in 2025; 2025 net profit was approximately VND 20.4 billion
An M&A transaction values more than current revenue. Investors buy the time spent developing products, building factories, creating brands, establishing operating standards and reaching customers. Businesses seeking higher long-term value should turn these capabilities into verifiable assets.
Suggested actions
Sources and updates
Updated by the Bài Học Kinh Doanh editorial team on September 1, 2026 using disclosures from Charoen Pokphand Foods, InfoQuest Thailand, Kaohoon International and company information. At publication, the parties had signed an agreement, but the transaction remained subject to conditions and was expected to close in mid-October 2026; this article therefore does not describe it as completed.
Last updated: 1 Sept 2026
Bài Học Kinh Doanh Editorial Team
Editorial Team | Bài Học Kinh DoanhBan Biên tập Bài Học Kinh Doanh tổng hợp và biên tập các nội dung về kinh doanh, thị trường, quản trị, công nghệ và khởi nghiệp, với mục tiêu giúp người đọc hiểu rõ vấn đề, nhìn thấy bài học phía sau dữ kiện và có thêm cơ sở cho các quyết định thực tế.
View author profile