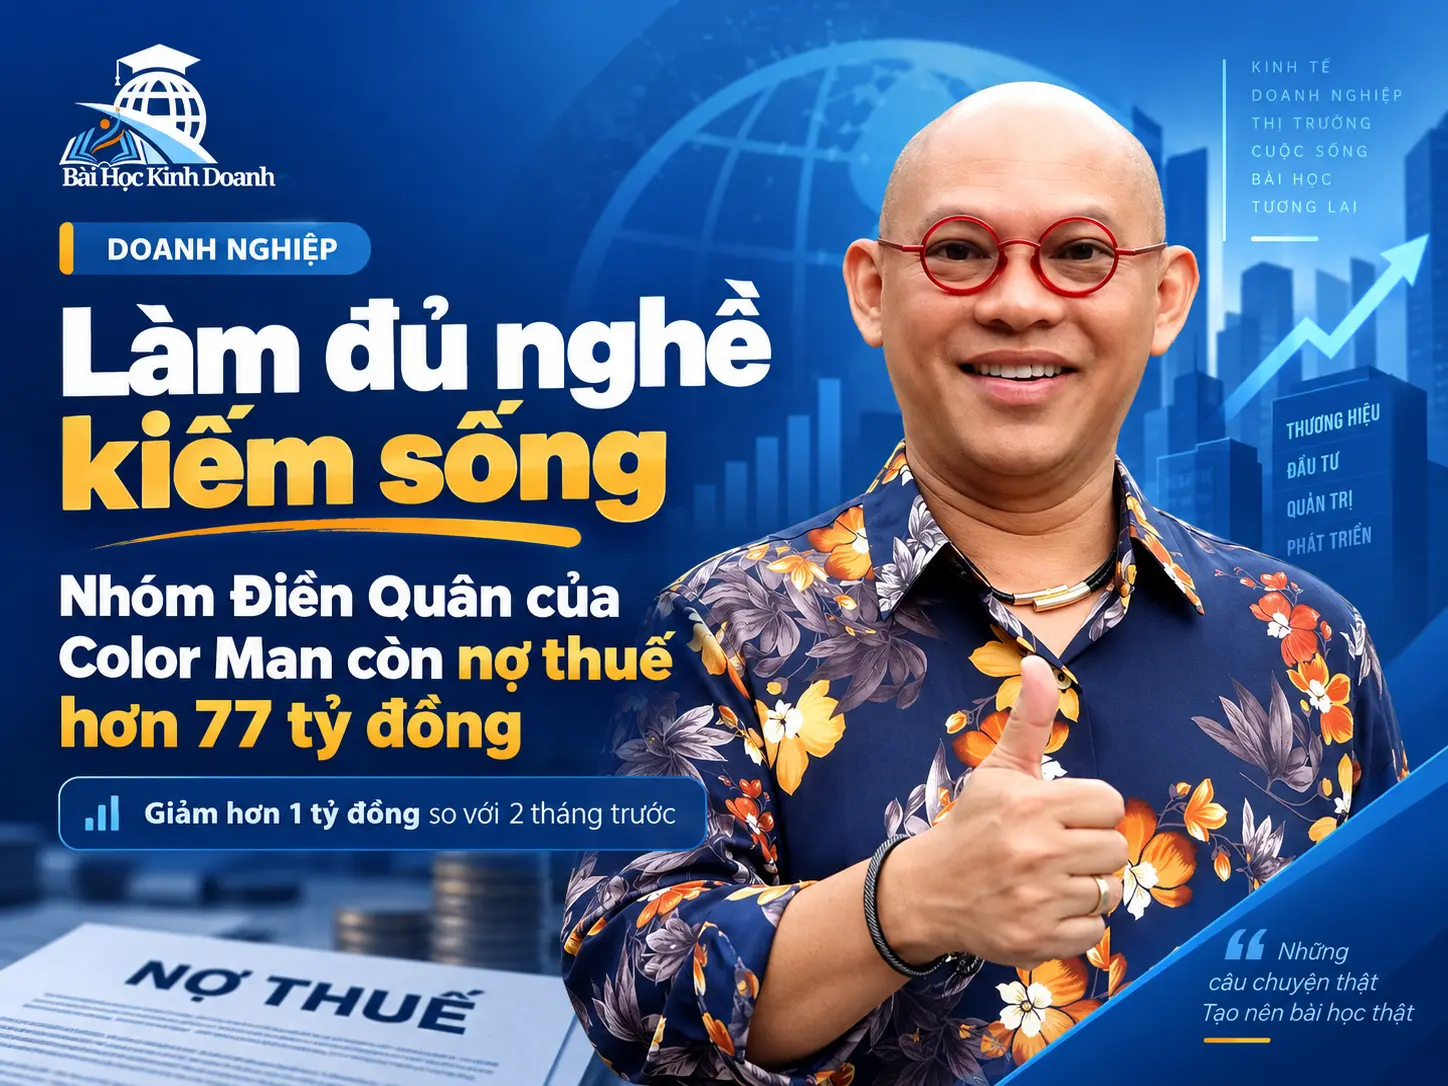
Điền Quân once had a major presence in southern Vietnam’s media and gameshow market. In a public list cited by the press on September 9, 2026, three group entities had over VND 77.1 billion in tax and state-budget obligations as of July 31, 2026. This was approximately VND 1.35 billion below the VND 78.45 billion disclosed two months earlier, but still represented a substantial financial obligation. The lesson is not a simple contrast between fame and hardship, but the gap between brand reach, revenue, profit and actual cash available to meet obligations when due.
What does VND 77.1 billion describe?
According to CafeF on September 9, 2026, citing Tax Office 14, Ho Chi Minh City, three Điền Quân entities had total tax and state-budget obligations exceeding VND 77.1 billion as of July 31, 2026. The reported breakdown includes over VND 30.8 billion for Công ty Cổ phần Điền Quân Group, over VND 24.5 billion for one Điền Quân Network entity and over VND 21.7 billion for another Điền Quân Network entry.
The subject must be read correctly. The list reflects obligations of organizations or entities named Điền Quân; it is not evidence that Đỗ Văn Bửu Điền personally owes over VND 77 billion. Color Man’s association with the story comes from his founding and management roles and public recognition of his connection to the brand.
Publicly disclosed tax arrears must also be distinguished from a general conclusion about overall business health. The list shows budget obligations at one moment, but not complete revenue, assets, receivables, arrangements with the tax authority or future repayment ability. It is an important signal, not the whole picture.
Debt has declined, but interpret the signal cautiously
Two months earlier, Tuổi Trẻ and Dân Trí cited VND 78.45 billion. Compared with over VND 77.1 billion in the current period, the reduction is approximately VND 1.35 billion. The direction is positive because disclosed total obligations did not continue increasing over this comparison.
An absolute decline matters only alongside three questions: was it caused by payments, data adjustments or recognition changes; is the pace sufficient relative to new obligations; and how is the remaining payment schedule being handled? Without detailed documents from each business or the authority, do not infer that a financial problem is solved merely from a lower number.
For managers, this is the difference between viewing a balance and a trajectory. The balance shows where a business stands; the trajectory shows whether the system is improving or deteriorating. Good management requires both, with specific funding sources and deadlines for each obligation.
From a gameshow production machine to experiments with multiple models
Điền Quân became widely known through producing shows such as Thách thức danh hài, Giọng ải giọng ai, Sàn đấu ca từ and Thiên đường ẩm thực. The model relied on content development, large-scale production, television distribution and monetizing mass attention.
As gameshow production declined sharply, Color Man became more visible in food, beverages, restaurants and personal content creation. This is a very different trajectory from a media system producing programs for mass audiences.
Adding models can create new revenue opportunities, but diversification does not automatically equal successful restructuring. Each new shop, brand or entity brings its own working capital, fixed costs, tax obligations and operational risks. Without matching measurement systems, many small experiments can fragment management without generating enough money to address the old burden.
Brand reach is not financial health
A media brand can have large audiences, famous artists, widely broadcast shows and strong discussion-generating power. Reach is a marketing asset; it becomes financial health only when converted into revenue with margins, timely collections and cash flow sufficient for obligations.
Revenue is not cash either. A contract may be recognized before the customer pays; a show may attract viewers while production, staffing, licensing and distribution costs were incurred earlier. When receipts take longer than payments, a business can grow on reports while lacking money for taxes or suppliers.
Founders should therefore separate four often-confused measures: fame, revenue, accounting profit and free cash flow. The first opens doors; the other three determine whether the business can continue.
Tax obligations often provide the final test of cash-flow discipline
Tax is not an unexpected expense when filing schedules, reserves and reconciliation are clear. During hardship, however, tax money can be viewed as temporary funds for wages, operations or working capital. This may prolong short-term survival while allowing obligations to accumulate and legal complexity to increase.
A healthy financial system separates money payable from money available to use. Obligations also need reporting by legal entity, since one model having cash does not mean it can freely subsidize another without contractual, accounting and tax consequences.
Once debt exists, the problem is not simply finding new revenue. Businesses must map creditors and obligations, prioritize deadlines and consequences, negotiate using verifiable data and prevent new arrears. If new cash only sustains operations while old obligations do not fall, restructuring is not truly advancing.
The restructuring lesson: deliberately become smaller
Restructuring is not renaming a brand or adding industries. It means deciding which models can still generate cash, which assets to sell, costs to cut, entities to retain and obligations to address first. The hardest decision is often stopping an activity that once brought fame but no longer suits the market or current capital capacity.
Evaluate each model through cash flow after all costs, taxes and working capital. A shop with good revenue but high inventory, slow collections or constant advertising subsidies may not create real value. A smaller activity with faster turnover and fewer fixed costs may be more suitable during recovery.
Becoming smaller does not mean failure. In many cases it buys time, lowers break-even and restores options. But downsizing has value only alongside disciplined resolution of old obligations; merely shifting attention to a new model leaves the underlying problem intact.
Five questions business owners should ask themselves
First, if revenue falls 30% over six months, what should be cut first, and who has authority to decide? Second, how much of the account balance can truly be used after taxes, wages and upcoming payments?
Third, which models or entities generate cash, which only generate revenue, and which consume cash? Fourth, which obligations can be negotiated and which need priority because of legal or reputational risks? Fifth, when starting a new direction, is the business using surplus resources or further fragmenting an already pressured team?
The Điền Quân story merits attention not for the contrast between glory and hardship. Its value lies in how a system once grown through reach confronts less glamorous but survival-determining issues: cash, obligations, the speed of downsizing and the discipline of starting again.
- Over VND 77.1 billion is the press-reported total from the tax authority’s list for three Điền Quân entities, not Đỗ Văn Bửu Điền’s personal tax debt
- The approximately VND 1.35 billion reduction is a positive movement, but insufficient to establish that financial obligations have been substantially resolved
- Media reach and brand strength cannot replace cash-flow discipline, tax reserves and timely downsizing
- When an old model declines, restructuring must address legal entities, fixed costs and obligation schedules, rather than simply add new revenue sources
A business can be highly famous yet financially strained if cash arrives more slowly than payments fall due. The central lesson is to manage tax money, working capital and fixed costs separately; when markets change, downsizing and restructuring speed matter as much as earlier expansion speed.
Suggested actions
Sources and updates
Independent analysis prepared and updated by the Bài Học Kinh Doanh editorial team on September 9, 2026 using press reports citing the public list of Tax Office 14, Ho Chi Minh City. Over VND 77.1 billion is dated July 31, 2026 and includes tax and state-budget obligations of three entities classified within the Điền Quân group. It is not Đỗ Văn Bửu Điền’s personal debt and does not itself establish each business’s current liquidity, solvency or performance. The approximately VND 1.35 billion decrease is compared with the earlier VND 78.45 billion list. The supplied illustration was optimized for the web; image figures do not replace source data. The content makes no legal determination and does not represent the tax authority or mentioned businesses.
Last updated: 9 Sept 2026
Bài Học Kinh Doanh Editorial Team
Editorial Team | Bài Học Kinh DoanhBan Biên tập Bài Học Kinh Doanh tổng hợp và biên tập các nội dung về kinh doanh, thị trường, quản trị, công nghệ và khởi nghiệp, với mục tiêu giúp người đọc hiểu rõ vấn đề, nhìn thấy bài học phía sau dữ kiện và có thêm cơ sở cho các quyết định thực tế.
View author profile