Household businesses can submit supplementary declarations for errors such as omitted revenue or incorrect tax figures. Identify the error and period, then monitor both filing results and additional payment obligations.
Identify the error before making changes
For shop owners juggling sales, staff, payment reconciliation and bookkeeping, filing mistakes can happen. Missing revenue or an incorrect entry can make a return inconsistent with actual records.
Submitting a return does not end the opportunity to correct it. Tax administration rules allow supplementary declarations for errors in submitted filings. The procedure depends on the correction and the filing’s status.
Before changing a number, reconcile the filed return with revenue records, invoices, supporting documents and sales data. Identify the affected period, omitted or duplicated revenue, the fields to correct, the correct figures and any impact on tax payable.
Correcting a rejected filing and supplementing an accepted return are different situations. Check the processing notice before preparing another submission.
A reconciliation table listing filed figures, corrected figures, differences, reasons and supporting evidence makes review easier and reduces repeated corrections.
Check which form applies in 2026
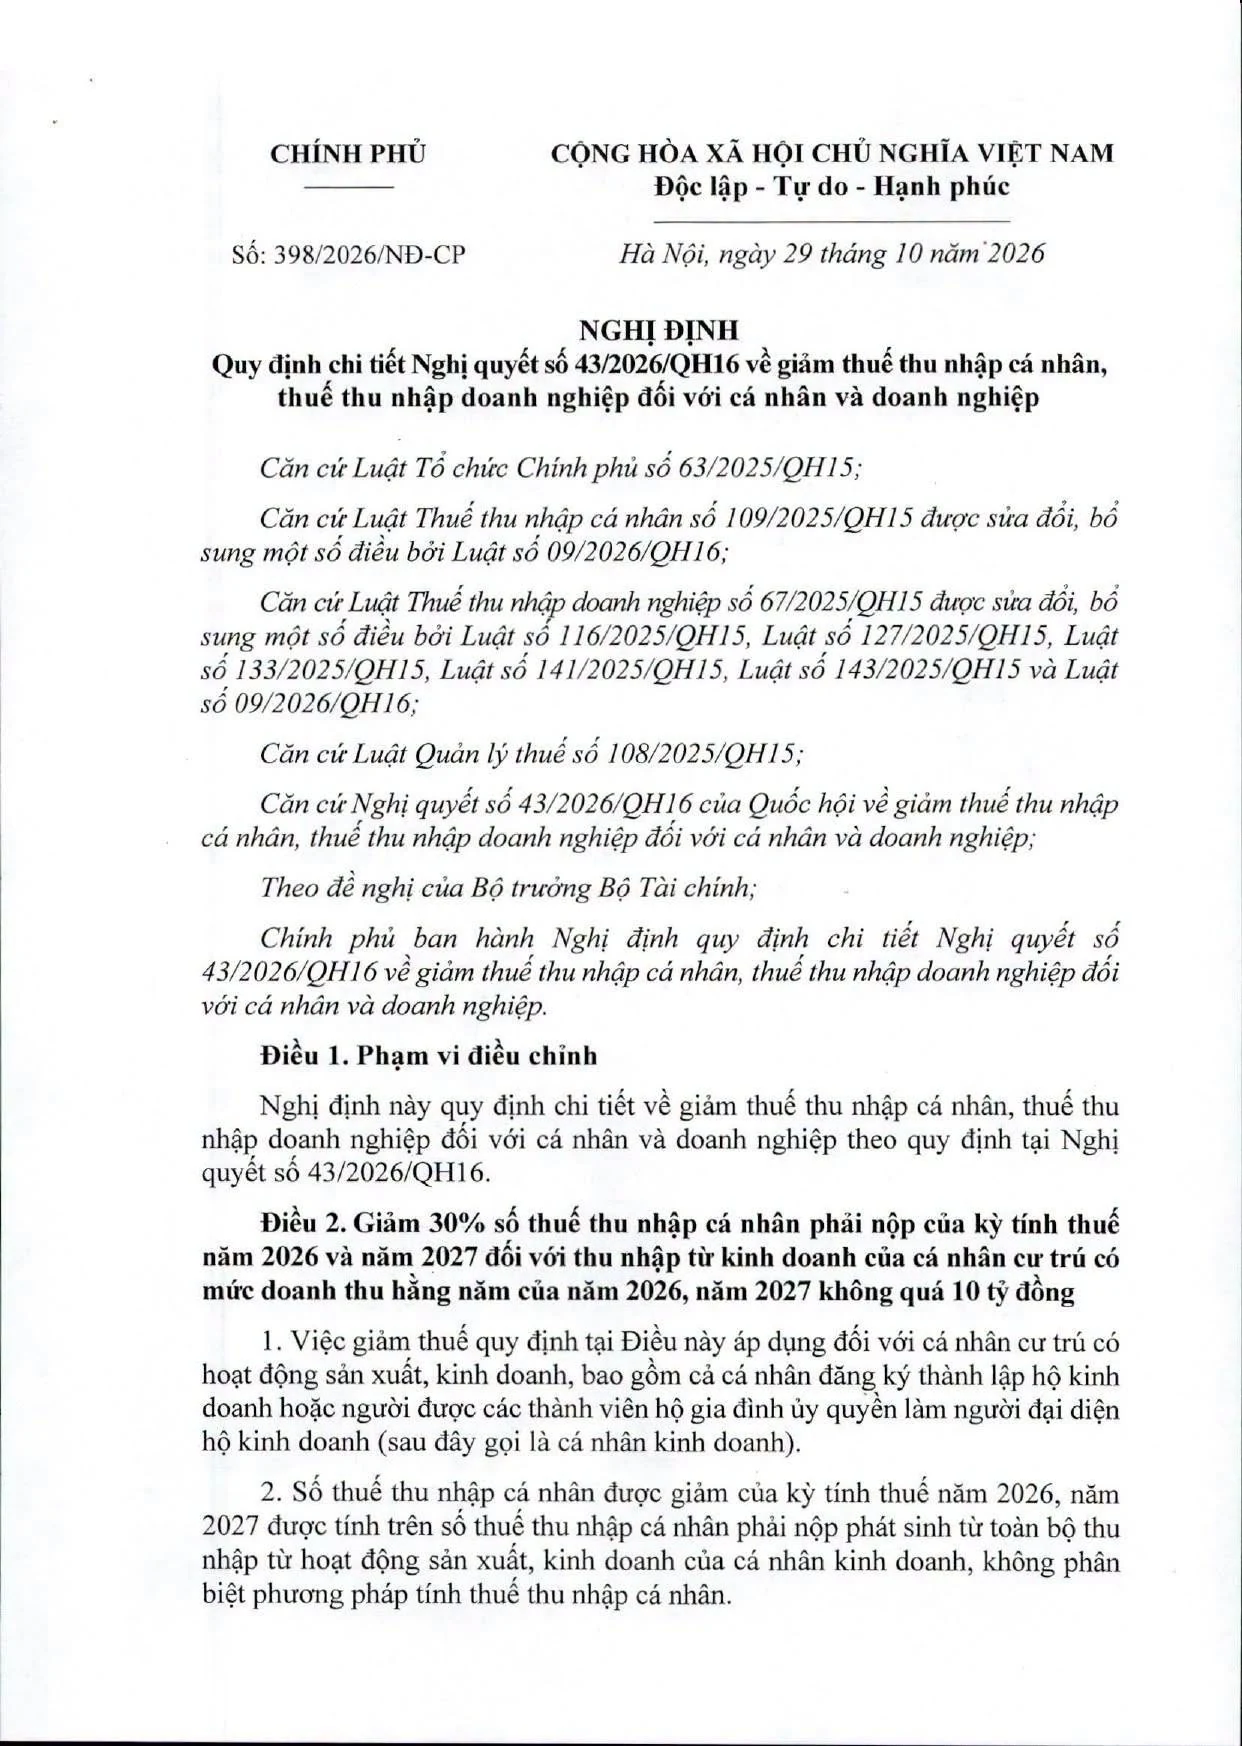
Do not reuse an old form for every period. The Government Portal’s May 30, 2026 procedure cites form 01/CNKD under Circular 50/2026/TT-BTC. Guidance published in September 2026 also notes that household and individual businesses subject to separate filing rules must follow the corresponding guidance.
Match the form to the tax period, calculation method and original filing. A guide labeled “2026” does not necessarily apply to every case.
Submitting a supplementary filing online
Start at the Tax Department’s administrative procedures portal: https://dichvucong.gdt.gov.vn/tthc/homelogin. The following is a reference workflow; labels and authentication options may differ by account, filing type and system version.
Step 1: Sign in to the correct account using a supported method and verify the taxpayer details.
Step 2: Look up the original filing by type, tax period and submission date. Read the processing notice to check whether it has been accepted.
Step 3: Select the supplementary filing function for the relevant return where available. Do not create a new initial return as a substitute.
Step 4: Prepare and review the filing. Complete it online or upload XML where supported. Check the period, amendment number, corrected figures and attachments.
Step 5: Authenticate, submit and retain the result. Save the filing reference and monitor acceptance or requests for corrections.
This reference workflow draws on TruePOS interface guidance. Its screenshots use the TT40 form, so check the current form for the actual tax period rather than following them mechanically.
Filing an amendment does not settle the tax payment
Amending a return and paying tax are separate actions. If the correction increases tax due, determine the additional payment and any applicable late-payment amount. Voluntary correction does not guarantee exemption from penalties; the authority considers the facts and applicable rules.
If the correction reduces declared tax or may create an overpayment, check the procedure with the managing tax authority. Do not assume an immediate refund or automatic deduction from the next period.
For filings under inspection or audit, or already covered by a formal conclusion, consult the tax authority before applying the standard workflow.
Mistakes to avoid
Wrong period: discovering an error this month does not mean it belongs to this month’s tax period.
Ignoring related fields: a revenue correction may affect multiple lines. Review all affected entries before submission.
Confusing net receipts with revenue: bank deposits may reflect deducted fees, collections for others or refunds. Establish what each amount represents.
Confusing submission with acceptance: continue monitoring processing notices after sending the return.
Not keeping records: retain the original return, amendment, reconciliation, notices and payment evidence together by period.
An operational lesson: reconcile revenue before filing day
Amendments correct mistakes, but regular reconciliation reduces rework. Each week, compare sales data, invoices, cash, bank transfers and platform reports. Log and resolve discrepancies before closing the period.
Before filing, arrange a second review, even if it simply means checking the reconciliation and key fields again.
Accurate tax filing also helps owners understand revenue, control cash flow and prevent small discrepancies from accumulating. When an error appears, check the original return, establish the correct figures and choose the appropriate correction procedure.
- Distinguish rejected filings from accepted returns.
- Choose the correct form and tax period.
- A supplementary filing does not mean all tax has been paid.
Regular reconciliation reduces filing errors and improves cash-flow control.
Suggested actions
Information checked on October 26, 2026. For individual filings, confirm the rules for the relevant period and the managing tax authority’s guidance.
Last updated: 27 Oct 2026
Bài Học Kinh Doanh Editorial Team
Editorial Team | Bài Học Kinh DoanhBan Biên tập Bài Học Kinh Doanh tổng hợp và biên tập các nội dung về kinh doanh, thị trường, quản trị, công nghệ và khởi nghiệp, với mục tiêu giúp người đọc hiểu rõ vấn đề, nhìn thấy bài học phía sau dữ kiện và có thêm cơ sở cho các quyết định thực tế.
View author profile