Review contracts and evidence, determine revenue correctly, then calculate relief on eligible tax.
1. Separate own-account sales from agency transactions
List purchase, sales, agency and consignment contracts and identify the invoicing party. Do not automatically treat all agency collections, or commission alone, as revenue: review the contract substance, invoicing responsibilities and applicable rules. Assess eligibility by taxpayer, not by brand or warehouse.
2. Document discounts and returns
Track order IDs, recorded revenue, discounts, returns, adjustment invoices, receivables and receipts. Net receipts after discounts are not automatically the eligibility figure. Companies must review the revenue scope in Article 3(3), including financial revenue and other income; reductions need supporting grounds, not merely an internal sales sheet.
3. Reconciliation example and monthly close
Illustration: sales records show VND 8 billion but bank receipts are VND 7.4 billion because of receivables and deductions. Explain each component of the VND 600 million difference instead of automatically reducing revenue to receipts. Reconcile receivables, customer confirmations, invoices and return records before determining eligibility.
4. Calculate relief and choose the filing route
Illustration: eligible income tax before this relief, after other incentives if applicable, is VND 50 million. If all conditions are met, relief is VND 15 million and the remainder VND 35 million. Do not multiply revenue by 30%; this is not VAT relief. Companies review sales, service and financial revenue, other income and exclusions; individuals determine revenue under the rules cited in Article 2.
Business individuals review Form 01 with the applicable return. Withholding or filing agents use Form 02 for their responsibilities. Companies self-determine relief when making quarterly CIT payments; the individual’s Form 01 is not a company CIT-relief form.
Suggested workflow: close the period, assess eligibility, calculate tax before relief, calculate relief, check official forms, file through the applicable electronic tax channel, and retain signed files, acknowledgements and payment evidence. These are working steps, not universal portal button names. Review amendment rules for missed relief rather than arbitrarily deducting it from a later payment.
5. Monitor the ceiling and prepare the evidence pack
Individuals exceeding VND 10 billion actual annual revenue reverse relief using Form 03 with the filing for the threshold-crossing period. The specified late-payment exclusion ends at that period’s filing deadline. Companies pay the shortfall and follow Article 24(3) of Decree 252/2026/ND-CP rather than assuming the individual rule applies.
Assign someone to update monthly cumulative revenue and outstanding orders or contracts, with a review date. Retain source records, calculations and reconciliations for independent review. The following is a recommended internal evidence pack, not a universal mandatory attachment list.
| Item | Action |
|---|---|
| Contracts and appendices | Match source records, responsible staff and recognition dates. |
| Invoices, evidence and reconciliation schedules | Match source records, responsible staff and recognition dates. |
| Receivables, cash flows and year-end forecasts | Match source records, responsible staff and recognition dates. |
6. A practical monthly reconciliation worksheet
Create an internal worksheet with the groups below. Link each row to a transaction or contract and add amount, proposed recognition period, supporting basis and review status. It supports review and does not replace accounting records, returns or official forms.
| Data group | Recording and review |
|---|---|
| Order and customer IDs | Match sales orders, invoices, delivery records and buyer under one ID. |
| Discounts and returns | Record reasons, terms, adjustment evidence and period; have accounting determine the effect. |
| Receivables and collections | Separate opening balance, movements, collections and closing balance; flag advances and offsets. |
| Items awaiting review | Log missing invoices, unconfirmed returns and differences with an assigned owner. |
7. Close the records and resolve exceptions
Step 1: Operations exports source data and records the cutoff. Step 2: The reconciliation owner matches transactions, checks duplicates and explains differences. Step 3: Accounting determines revenue, tax and relief eligibility. Step 4: A reviewer checks calculations against evidence before filing. This is a suggested internal workflow; small businesses may combine roles but should retain an independent review.
Separate supported records from items needing clarification. Assign an owner, expected resolution date and a specific question for accounting or the tax authority. Pending internal reconciliation does not extend a filing deadline; follow the actual applicable timetable and procedure.
- Assess revenue within the taxpayer’s proper scope, not per transaction.
- Reconcile receipts, revenue and collections for others before applying relief.
- Reduce eligible tax without assuming one tax rate for the sector.
Correct relief depends on traceable revenue and tax records.
Suggested actions
Frequently asked questions
Does the reduction apply to every tax?
No. This relief covers eligible business PIT or CIT, not automatically VAT or every other tax.
Do different sales channels have separate ceilings?
Do not assess channels separately. Aggregate the proper taxpayer scope under Article 2 or 3 of Decree 398.
A customer offsets receivables with returns but records are incomplete?
Log the offset separately, obtain reconciliation confirmation and complete supporting evidence. A lower receivable does not by itself justify deleting revenue. Accounting should review whether a filed return needs amendment and for which period.
Should revenue be split by channel to stay below VND 10 billion?
Do not arbitrarily split eligibility by channel, warehouse or receiving account. Identify the taxpayer and the statutory revenue scope; internal reporting changes do not change transaction substance.
Series: 30% tax relief: sector guides
- 30% PIT and CIT reduction: guidance for revenue up to VND 10 billion
- Retail and online sales: a guide to the 30% tax reduction in 2026–2027
- Restaurants and cafés: 30% tax relief and multi-location revenue reconciliation
- Services and contract manufacturing: 30% tax relief from contract review to finalization
- Construction and interiors: 30% tax relief and project revenue review
- Transport and logistics: 30% tax relief and freight, COD and collection reconciliation
- Salons and spas: 30% tax relief and package and prepaid-card revenue
- Wholesale and distribution: 30% tax relief and sales reconciliation
- Accommodation and hotels: 30% tax relief, OTA payouts and deposits
- Marketing and digital services: 30% tax relief and advertising budgets
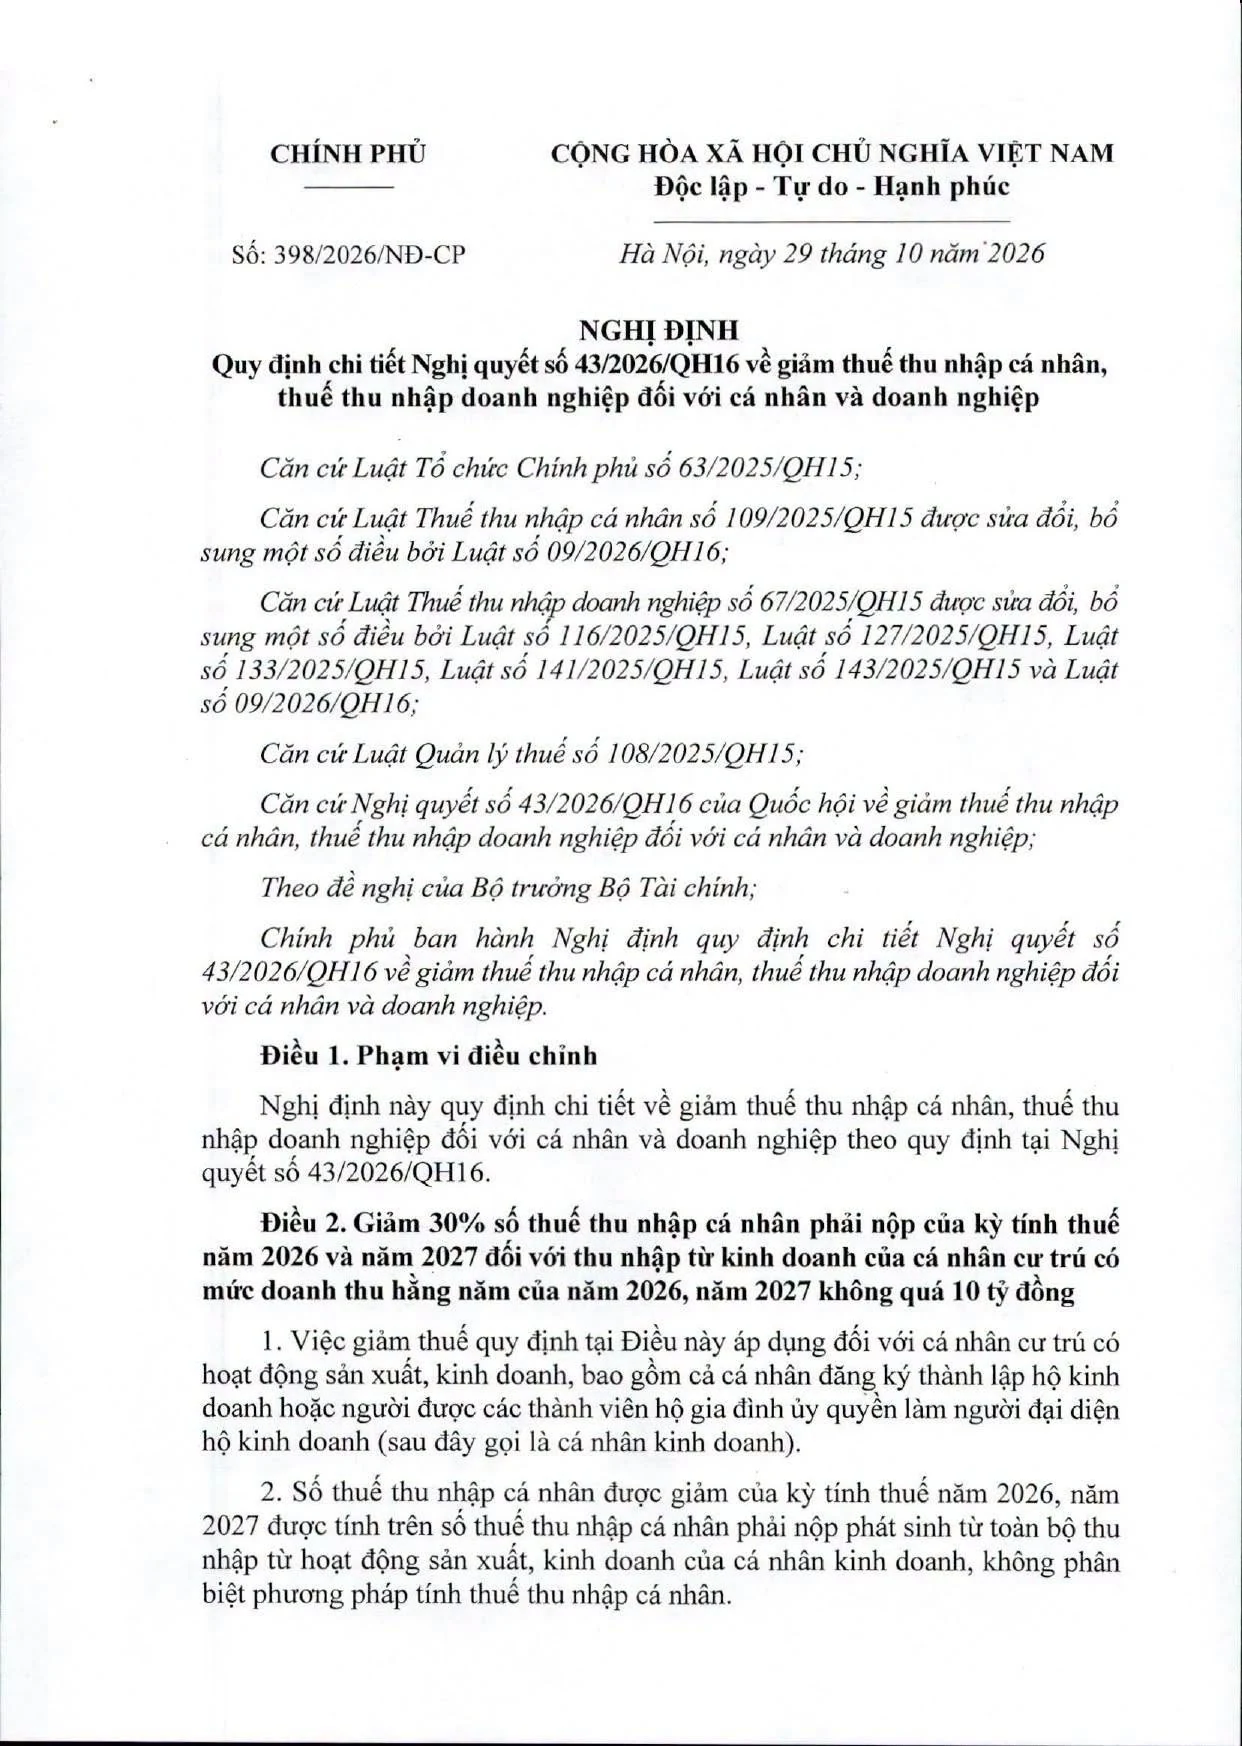
Updated 3 November 2026. Based on Articles 2 and 3 of Decree 398/2026/ND-CP. Examples are illustrative; adapt working checklists to the actual activity and tax method.
Last updated: 3 Nov 2026
Bài Học Kinh Doanh Editorial Team
Editorial Team | Bài Học Kinh DoanhBan Biên tập Bài Học Kinh Doanh tổng hợp và biên tập các nội dung về kinh doanh, thị trường, quản trị, công nghệ và khởi nghiệp, với mục tiêu giúp người đọc hiểu rõ vấn đề, nhìn thấy bài học phía sau dữ kiện và có thêm cơ sở cho các quyết định thực tế.
View author profile