A contribution-margin-based break-even ROAS formula, a VND 300,000 order example and reconciliation of cancellations and returns. Part of the Profitable Selling series, using a hypothetical example and step-by-step guidance.
What does ROAS tell you?
ROAS is ad-attributed revenue divided by advertising spend. Spending VND 10 million and recording VND 40 million in revenue corresponds to a ROAS of 4. It does not deduct product costs, packaging, service fees or operating costs.
Two shops with a ROAS of 4 can have different results. A shop with higher pre-advertising contribution has more room to pay acquisition costs. There is therefore no universally good ROAS for every product.
The contribution-level break-even formula
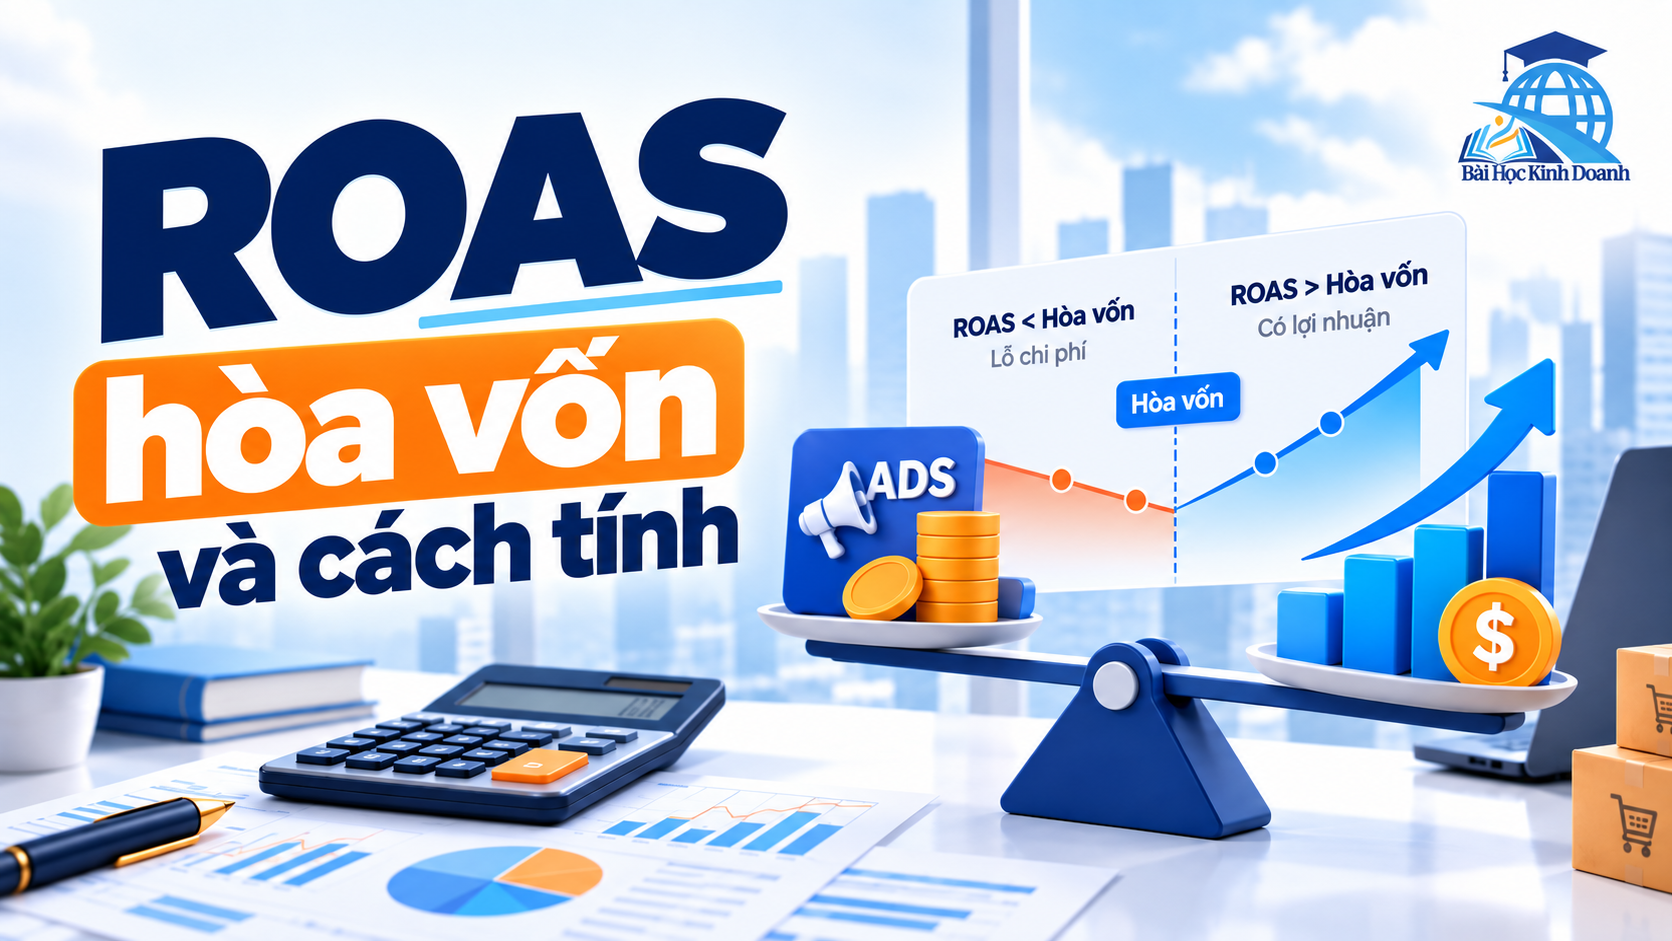
First calculate pre-advertising contribution margin = (net revenue minus all non-advertising variable costs) divided by net revenue. With a positive margin, break-even ROAS at this level = 1 divided by pre-advertising contribution margin.
Revenue and costs must cover the same scope: products, period and handling of returns. This threshold only makes post-advertising contribution zero; it does not cover rent, fixed salaries or overhead. If the pre-advertising margin is zero or negative, no finite ROAS can resolve that cost structure.
A step-by-step example
Assume a completed order has VND 300,000 in net revenue, VND 165,000 in product costs and VND 45,000 in other variable costs. Pre-advertising contribution is VND 90,000, or 30%. The ROAS threshold is 1/0.30, approximately 3.33.
To retain VND 30,000 per order toward overhead and profit, maximum advertising spend per order is VND 60,000. The model's target ROAS becomes 300,000/60,000 = 5. This is an assumption-based target, not an industry benchmark.
Why can reports look good while cash remains short?
Ad-report revenue may not fully reflect cancellations, returns or order-value changes. Assigning one transaction to multiple touchpoints can also make channel-report revenue totals differ from the order ledger.
Use completed orders as the reconciliation reference, keep the same measurement period and state reporting lag. Do not add revenues from multiple platforms and assume they all represent incremental revenue generated by advertising. Whether a customer would buy without seeing an ad is a different question from how a report attributes revenue.
When increasing budgets, examine the increment
Hypothetically, a budget rises from VND 10 million to VND 15 million while revenue increases from VND 50 million to VND 65 million. Overall ROAS after the increase remains 4.33, but the additional budget generates ROAS of only 15/5 = 3. With comparable other conditions, this signals a need to revisit expansion efficiency.
Do not attribute the entire difference to ads if prices, promotions or stock availability changed simultaneously. Record those changes and set an experiment budget consistent with the contribution you can afford to lose.
A minimum tracking table
Track net revenue from completed orders, non-advertising variable costs, ad spend, post-advertising contribution and new customer counts. Separate product groups with different margins so a strong product does not conceal a loss-making one.
Recalculate the threshold whenever pricing or basket composition changes. Without reliable repeat-purchase data, first assess how much acquisition cost the first order can absorb, then add long-term customer value using actual data.
- Align metric scope and calculation methods.
- Use the shop's actual costs instead of a general benchmark.
- Assess effectiveness through contribution and customer experience.
Recalculate the threshold whenever pricing or basket composition changes. Without reliable repeat-purchase data, first assess how much acquisition cost the first order can absorb, then add long-term customer value using actual data.
Suggested actions
Series: Profitable selling
- Profitable selling: Four calculations to clarify before growing revenue
- What is break-even ROAS? Calculate it to avoid losing more as you advertise more
- How many more orders does a 10% discount require to maintain contribution?
- What is AOV? Five ways to increase order value while maintaining efficiency
- Calculate repeat customer rates and find out why customers have not returned
- What are CAC and LTV? Calculating acquisition costs and customer value
- How to calculate profit per order after marketplace fees, advertising and returns
- Practice case: shop revenue grows 25% in eight weeks—why does profit fall?
Sources and updates
Original guidance from the Bài Học Kinh Doanh editorial team. All calculation figures are hypothetical illustrations, not survey findings, industry benchmarks, or current fee schedules. The simple models support operational analysis and do not replace the business’s accounting reports.
Last updated: 27 Sept 2026
Bài Học Kinh Doanh Editorial Team
Editorial Team | Bài Học Kinh DoanhBan Biên tập Bài Học Kinh Doanh tổng hợp và biên tập các nội dung về kinh doanh, thị trường, quản trị, công nghệ và khởi nghiệp, với mục tiêu giúp người đọc hiểu rõ vấn đề, nhìn thấy bài học phía sau dữ kiện và có thêm cơ sở cho các quyết định thực tế.
View author profile