The National Assembly issued Resolution 43/2026/QH16, reducing personal or corporate income tax payable for the 2026 and 2027 tax periods by 30% for taxpayers meeting revenue conditions. The policy took effect August 24, 2026. The reduction applies to tax payable, not revenue, and does not mean the tax rate automatically falls by 30%.
What does Resolution 43/2026/QH16 provide?
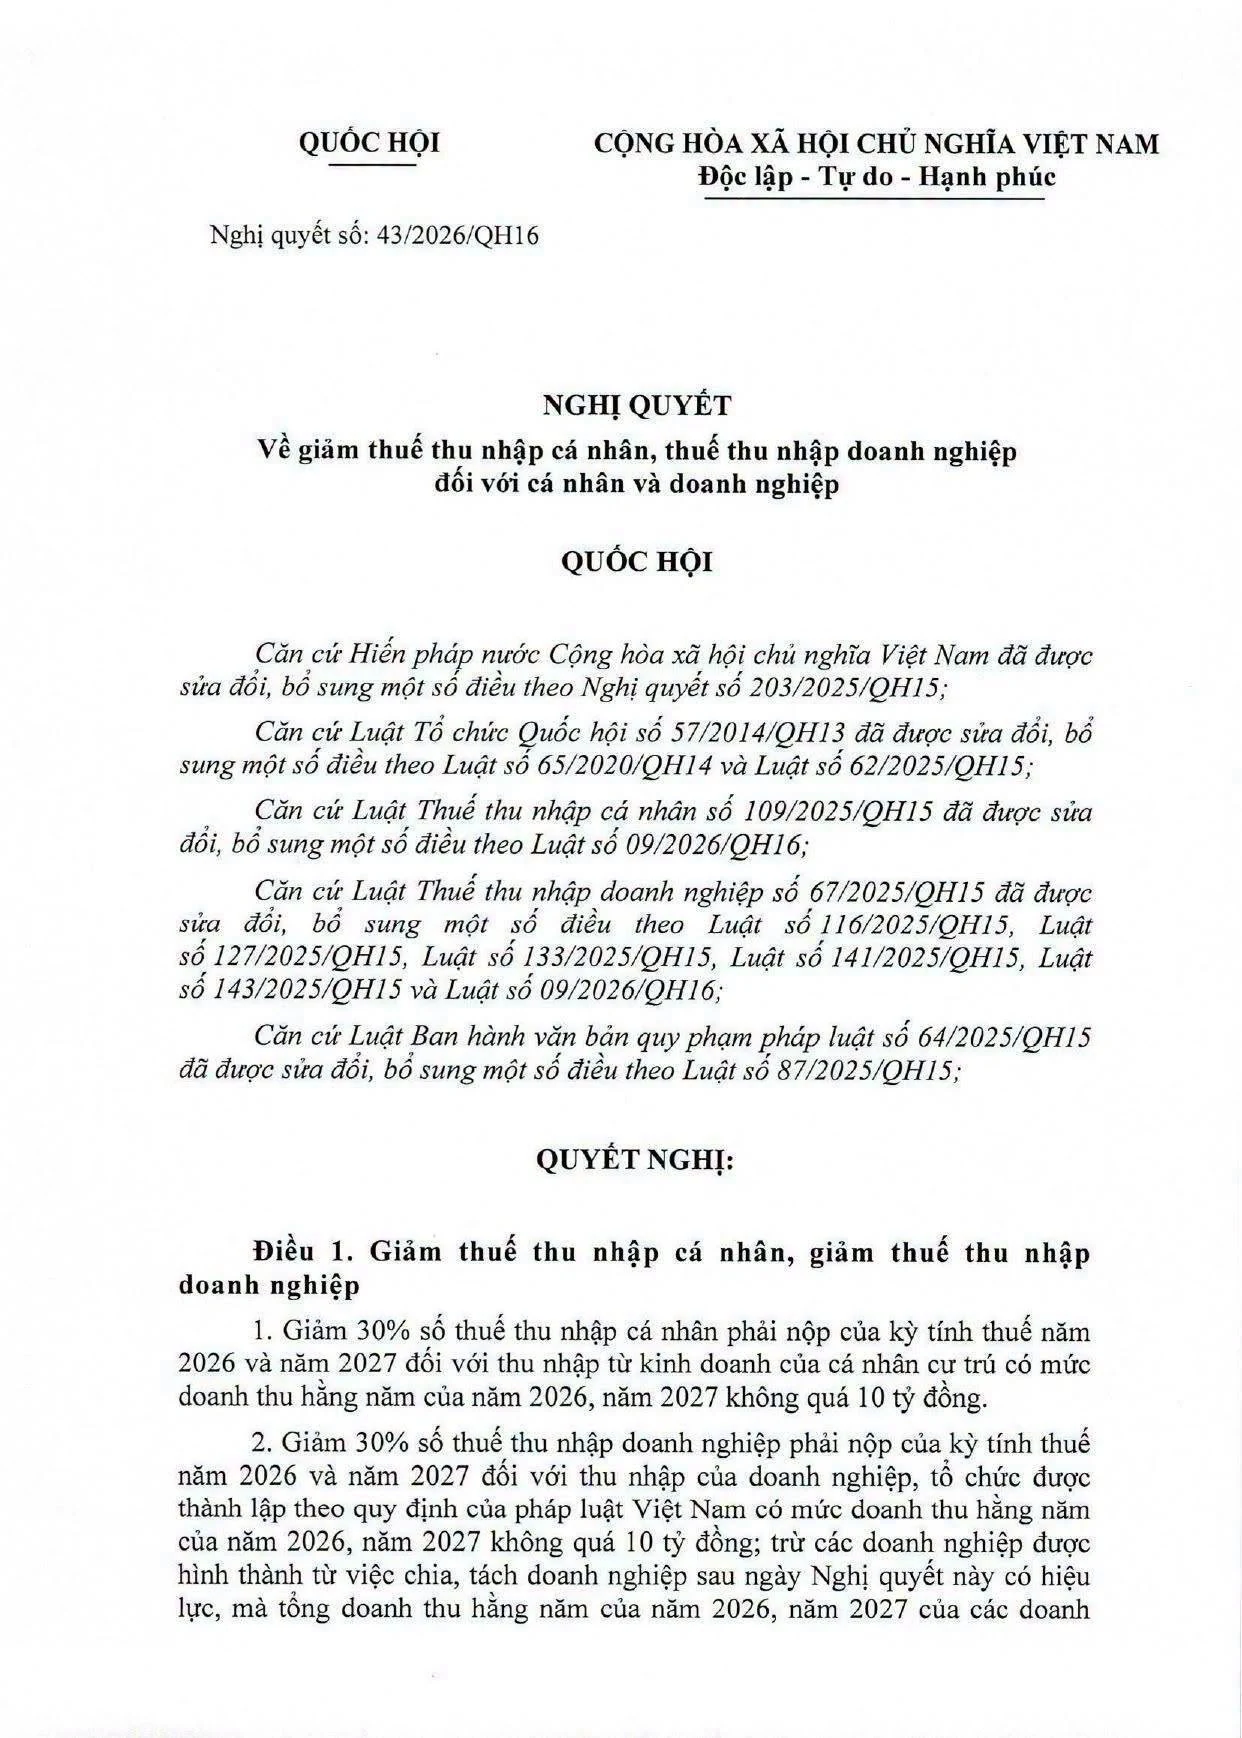
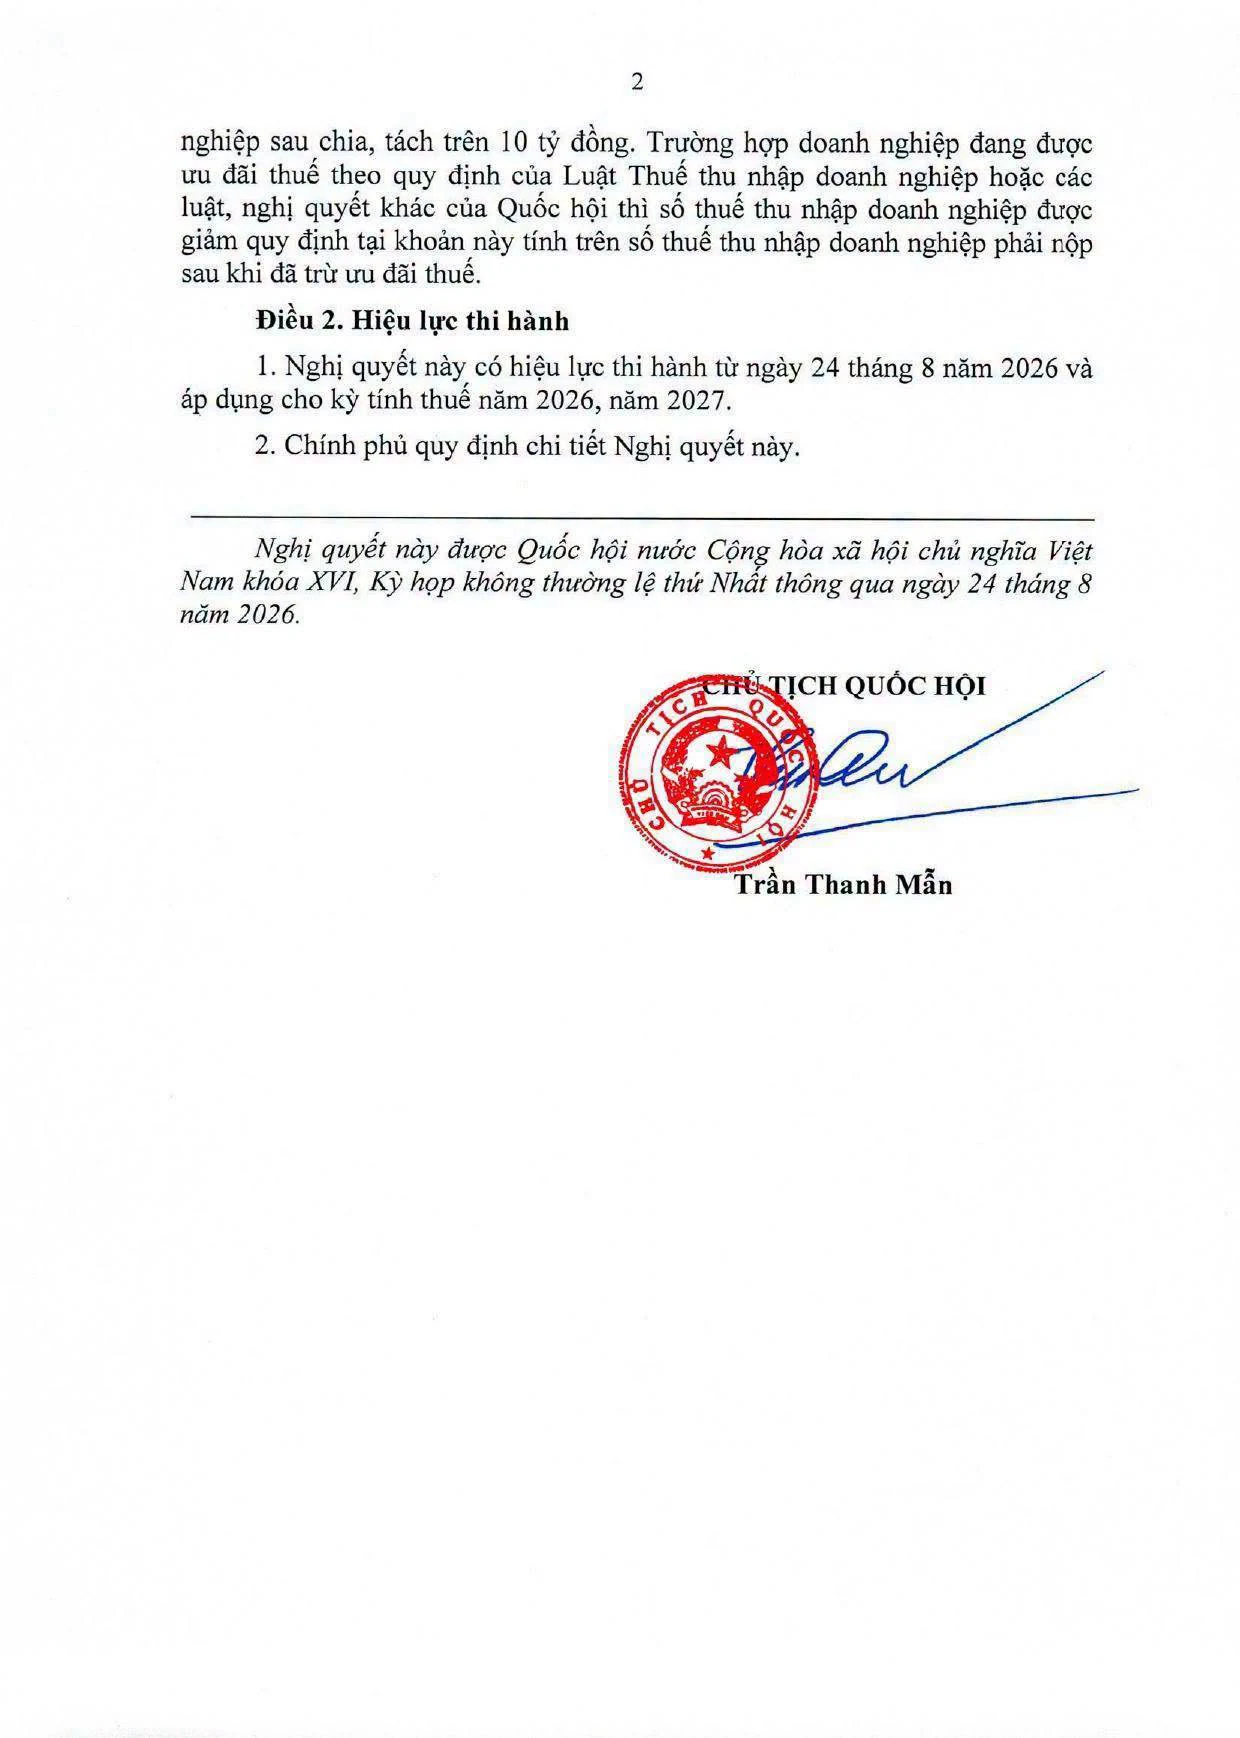
The 16th National Assembly adopted Resolution 43/2026/QH16 on August 24, 2026, effective immediately. It applies to the 2026 and 2027 tax periods, reducing personal income tax on business income and corporate income tax for eligible enterprises and organizations.
The document contains only two articles: Article 1 defines eligible taxpayers, reductions and exclusions; Article 2 specifies effectiveness and assigns detailed guidance to the Government. Taxpayers therefore need to read both the resolution and implementation guidance when issued.
Which business individuals receive the reduction?
Resident individuals with business income receive a 30% reduction in personal income tax payable for the 2026 and 2027 tax periods if annual revenue in each year does not exceed VND 10 billion.
Revenue conditions are assessed separately for each year. The resolution’s wording indicates that 2026 revenue determines eligibility for the 2026 tax period, and 2027 revenue for the 2027 period. Midyear situations or multiple income sources still require detailed guidance.
Which enterprises fall within the scope?
Enterprises and organizations established under Vietnamese law with annual revenue in each of 2026 and 2027 no higher than VND 10 billion receive a 30% reduction in corporate income tax payable for the corresponding tax period.
If an enterprise already receives corporate income tax incentives under legislation or another National Assembly resolution, the 30% reduction applies to remaining tax payable after incentives. This avoids calculating the reduction on an amount that has not reflected existing incentives.
Points to note when enterprises split or separate
The policy does not apply to enterprises created through splitting or separation after August 24, 2026 if their combined annual revenue in 2026 or 2027 exceeds VND 10 billion.
This provision aims to prevent dividing a business solely to place each entity below the revenue threshold. Businesses undergoing restructuring should retain records and check revenue aggregation under implementation guidance.
An easy misunderstanding: reducing tax payable
The resolution reduces tax payable by 30%, not revenue by 30%, and does not automatically reduce tax rates by 30%. Revenue no higher than VND 10 billion is an eligibility condition. Taxpayers calculate the tax obligation under the rules before determining the reduction.
For example, if an eligible enterprise has VND 100 million in corporate income tax payable after incentives, the resolution’s reduction is VND 30 million. Remaining tax is VND 70 million. This illustrates the interpretation and does not replace an actual tax filing calculation.
Effective date and next steps
The resolution takes effect August 24, 2026 but applies to the full 2026 and 2027 tax periods. The National Assembly assigns detailed rules to the Government, so filing procedures, revenue determination in special cases and supporting documents may receive further guidance.
For eligible small businesses and business individuals, the reduction may provide cash-flow, reinvestment and operating resources. Businesses should not automatically deduct tax before checking all applicable guidance and forms.
- Resident individuals with business income and revenue no higher than VND 10 billion in each year receive a 30% reduction in personal income tax payable
- Enterprises and organizations established under Vietnamese law with revenue no higher than VND 10 billion in each year receive a 30% reduction in corporate income tax payable
- The policy applies separately to the 2026 and 2027 tax periods; the Government will provide detailed rules
The crucial distinction is between revenue, taxable income and tax payable. The VND 10 billion threshold determines eligibility using each year’s revenue, while the 30% reduction applies to the tax obligation determined under the rules.
Suggested actions
Sources and updates
Updated by the Bài Học Kinh Doanh editorial team on September 1, 2026 using the full Resolution 43/2026/QH16 published by the Government Electronic Information Portal and two official document pages supplied by the user. This explains the policy for a general audience and does not replace tax-authority opinions or professional advice for individual filings. The resolution assigns detailed regulation to the Government, so taxpayers should continue monitoring guidance.
Last updated: 1 Sept 2026
Bài Học Kinh Doanh Editorial Team
Editorial Team | Bài Học Kinh DoanhBan Biên tập Bài Học Kinh Doanh tổng hợp và biên tập các nội dung về kinh doanh, thị trường, quản trị, công nghệ và khởi nghiệp, với mục tiêu giúp người đọc hiểu rõ vấn đề, nhìn thấy bài học phía sau dữ kiện và có thêm cơ sở cho các quyết định thực tế.
View author profile