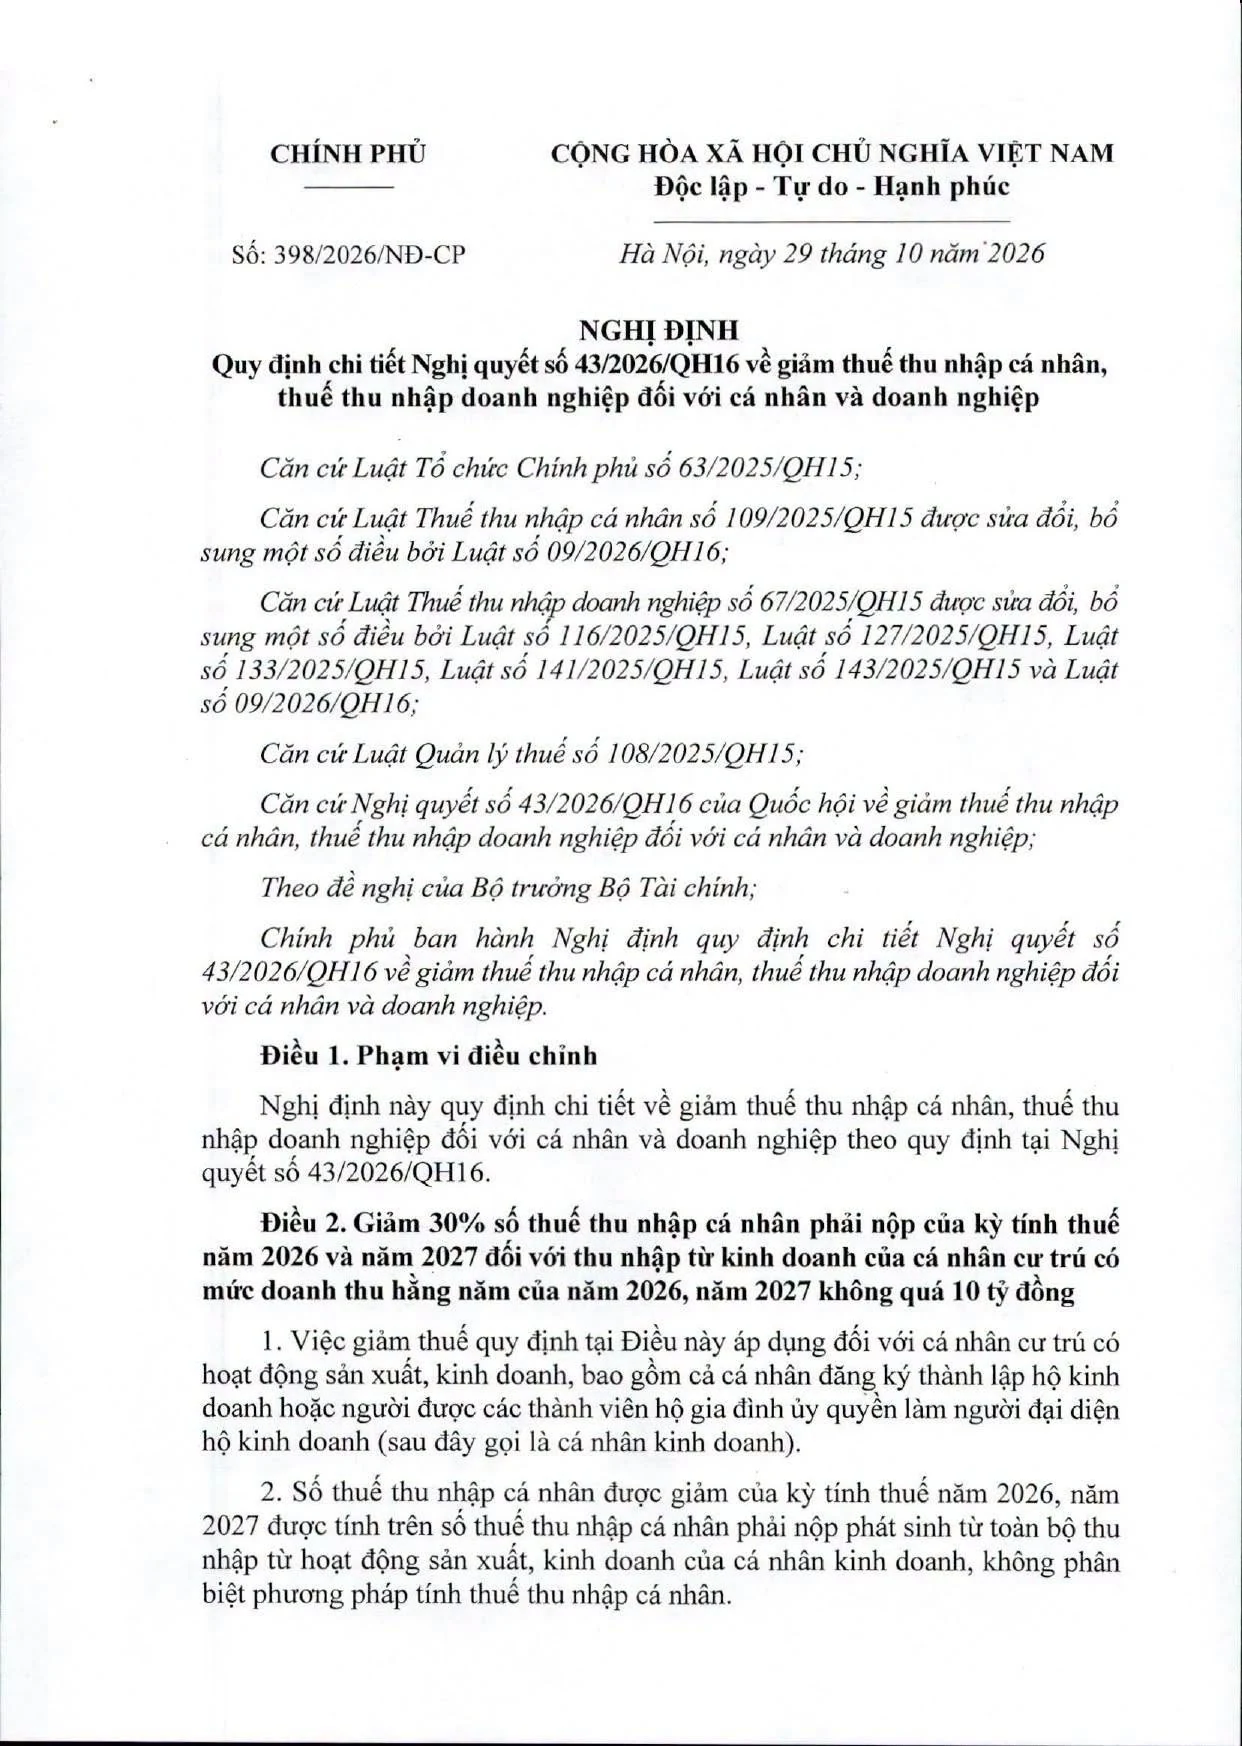
Identify the taxpayer, reconcile revenue sources, then apply 30% relief to eligible tax. This sector guide distinguishes business individuals from companies and provides numerical examples and evidence checklists.
1. One brand may involve several taxpayers
Map each outlet’s registered operator, invoice issuer, tax ID and legal relationship. A franchisee may be a separate taxpayer; a dependent branch is not automatically a separate company. Do not aggregate or separate outlets merely by brand name.
For companies, Article 3 includes dependent units and business locations reflected in annual consolidated financial statements. Household businesses follow the PIT route and should not substitute company CIT payment procedures for their own filings.
2. Reconcile POS, delivery and catering sales
Reconcile dine-in, takeaway, app delivery and catering by transaction ID. Match cash, card, QR and transfers to recorded revenue. Separate documented discounts, refunds, cancellations, deposits and amounts collected for others for accounting review.
Do not count app sales and corresponding app payouts twice. Delivery commissions and ingredient costs reduce cash or profit but are not automatically revenue deductions for eligibility. Vouchers, prepaid cards and catering deposits require case-specific review of recognition rules.
3. Work through a three-outlet company example
Illustration: dependent outlets have qualifying revenue of VND 3 billion, 2.5 billion and 2 billion, plus VND 0.2 billion of financial revenue and other income. The total is VND 7.7 billion. If all conditions hold and CIT before this reduction, after other incentives, is VND 150 million, relief is VND 45 million and the remainder is VND 105 million.
If expansion raises actual annual revenue to VND 10.2 billion, individual outlets being below the ceiling does not preserve eligibility. Update monthly forecasts, assign an owner to monitor the threshold and reserve cash for reversing previous relief. Company late-payment rules differ from those for business individuals.
4. Calculate relief on tax, not revenue
Separate illustrative household-business example: properly determined annual revenue is VND 2.4 billion and all conditions are met. Business PIT before relief is VND 36 million. Relief is 36 × 30% = VND 10.8 million; the remainder is VND 25.2 million. This does not imply a standard tax rate for the sector.
Companies apply 30% to CIT payable after any other tax incentives. Salary PIT, VAT and other obligations do not automatically receive this reduction. Where eligible tax is zero, this calculation produces no relief and no cash grant.
5. Choose the correct filing route and retain receipts
Business individuals review Form 01 with the applicable return. Withholding or filing agents use Form 02 for their responsibilities. Companies self-determine relief when making quarterly CIT payments; the individual’s Form 01 is not a company CIT-relief form.
Suggested workflow: close the period, assess eligibility, calculate tax before relief, calculate relief, check official forms, file through the applicable electronic tax channel, and retain signed files, acknowledgements and payment evidence. These are working steps, not universal portal button names. Review amendment rules for missed relief rather than arbitrarily deducting it from a later payment.
6. Monitor the ceiling and prepare the evidence pack
Individuals exceeding VND 10 billion actual annual revenue reverse relief using Form 03 with the filing for the threshold-crossing period. The specified late-payment exclusion ends at that period’s filing deadline. Companies pay the shortfall and follow Article 24(3) of Decree 252/2026/ND-CP rather than assuming the individual rule applies.
Assign someone to update monthly cumulative revenue and outstanding orders or contracts, with a review date. Retain source records, calculations and reconciliations for independent review. The following is a recommended internal evidence pack, not a universal mandatory attachment list.
| Item | Action |
|---|---|
| Legal entities and business locations | Reconcile with filings and keep retrievable records. |
| POS, delivery-app and invoice records | Reconcile with filings and keep retrievable records. |
| Refund, cancellation, voucher and deposit reconciliation | Reconcile with filings and keep retrievable records. |
- Do not substitute net cash receipts for properly determined revenue.
- Reduce eligible tax by 30%, not revenue.
- Monitor the annual VND 10 billion ceiling and reassess changes.
Correct tax relief starts with reconcilable revenue records, not a convenient number.
Suggested actions
Frequently asked questions
Does each outlet get its own VND 10 billion ceiling?
Not automatically. Locations belonging to the same company must be assessed within the statutory scope, including dependent units in consolidated statements.
Series: 30% tax relief: sector guides
- 30% PIT and CIT reduction: guidance for revenue up to VND 10 billion
- Retail and online sales: a guide to the 30% tax reduction in 2026–2027
- Restaurants and cafés: 30% tax relief and multi-location revenue reconciliation
- Services and contract manufacturing: 30% tax relief from contract review to finalization
- Construction and interiors: 30% tax relief and project revenue review
- Transport and logistics: 30% tax relief and freight, COD and collection reconciliation
- Salons and spas: 30% tax relief and package and prepaid-card revenue
- Wholesale and distribution: 30% tax relief and sales reconciliation
- Accommodation and hotels: 30% tax relief, OTA payouts and deposits
- Marketing and digital services: 30% tax relief and advertising budgets
Updated 1 November 2026. Based on Articles 2 and 3 of Decree 398/2026/ND-CP published by the Government Portal. Numerical examples are illustrative and checklists organize records; apply the rules to the actual records and tax method.
Last updated: 1 Nov 2026
Bài Học Kinh Doanh Editorial Team
Editorial Team | Bài Học Kinh DoanhBan Biên tập Bài Học Kinh Doanh tổng hợp và biên tập các nội dung về kinh doanh, thị trường, quản trị, công nghệ và khởi nghiệp, với mục tiêu giúp người đọc hiểu rõ vấn đề, nhìn thấy bài học phía sau dữ kiện và có thêm cơ sở cho các quyết định thực tế.
View author profile